When to Choose Collections vs. Legal Action: A Guide for Businesses and Lenders
An overdue invoice can begin as an administrative problem and become a recovery decision. Your team has sent reminders, followed up with the customer and perhaps offered a payment arrangement. When those efforts stop producing results, should you continue collections or consider legal action?
For businesses, financial institutions, equipment finance companies and auto lenders, the answer depends on more than the balance owing. The objective is to choose a proportionate next step based on the evidence, the likely recovery and the cost of getting there.
1. Compare the balance with the cost of recovery
A larger balance may justify more legal work, but there is no single dollar threshold that makes litigation worthwhile. A well-documented smaller account with a realistic payment source may deserve attention. A much larger debt with poor recovery prospects may not justify the same investment.
Consider filing fees, service costs, representation and possible enforcement expenses alongside the amount you reasonably expect to collect. Our block-fee approach helps corporate clients assess that decision with a defined scope and file budget.
2. Assess whether the debtor can pay
A judgment and a payment are different outcomes. Before starting proceedings, review the information available about the debtor’s financial position and any practical route to recovery.
For a business account, that might include whether the company is still operating, the correct legal entity behind the trading name and available information about its assets. For an individual borrower or guarantor, relevant information may include employment and assets, subject to applicable exemptions and enforcement rules.
Do not assume a director or owner is personally responsible for a company’s debt. Identify who agreed to pay and whether a separate, enforceable guarantee exists. Our guide to business searches explains why identifying the correct debtor matters.
3. Check the evidence and understand the dispute
Before escalating an unpaid account, assemble the records that explain what is owed and why:
- The contract, credit application or purchase order.
- Invoices and proof that the goods or services were supplied.
- An up-to-date account ledger showing payments and credits.
- Correspondence about the balance, complaints and payment commitments.
- Any guarantees, security documents or previous demands.
A customer who disputes the work requires a different assessment from one who accepts the balance but has stopped paying. Clear records help your representative evaluate the claim, respond to a defence and assess settlement options.
4. Consider location and the appropriate court
Outdated contact information can add cost and delay. Confirm the debtor’s legal identity and address before committing to proceedings. Locating the debtor may be a useful first step, provided it does not put a filing deadline at risk.
The appropriate forum depends on the amount, location and nature of the claim. We assist corporate clients with eligible matters in Ontario Small Claims Court, the Alberta Court of Justice Civil Division and British Columbia Small Claims Court.
For an introduction to court selection, watch Small Claims Court Limits in Ontario, Alberta and BC.
5. Review deadlines before another round of follow-up
An account’s age should be part of the initial review. Limitation periods depend on the applicable law and facts; do not assume every deadline runs from the invoice date, default or last payment. For example, Ontario’s Limitations Act, 2002 generally ties its basic two-year period to discovery of the claim, subject to the Act’s other provisions.
Have the applicable deadline assessed early. Do not assume that sending reminders or continuing negotiations preserves your ability to sue. If a deadline may be approaching, obtain advice promptly rather than waiting for another promised payment.
Choose the next step for the account
Continued collection efforts may make sense when communication is productive, a realistic payment arrangement is available or better information is needed. Legal action may warrant consideration when the evidence supports the claim, voluntary efforts have stalled and there is a reasonable recovery prospect. Settlement can remain an option throughout the process.
For a portfolio of overdue accounts, use consistent intake criteria so your team can distinguish files that need urgent review from those that need further information. Our short video on accounts receivable recovery for medium and large businesses introduces that structured approach.
Precision Paralegal Services works with corporate clients to assess the account, agree on a budget and identify the next practical step. Learn why businesses and lenders choose our team, or book a consultation to discuss an overdue account or portfolio of receivables.
Explore our corporate debt recovery services for businesses and lenders in Ontario, Alberta and British Columbia.
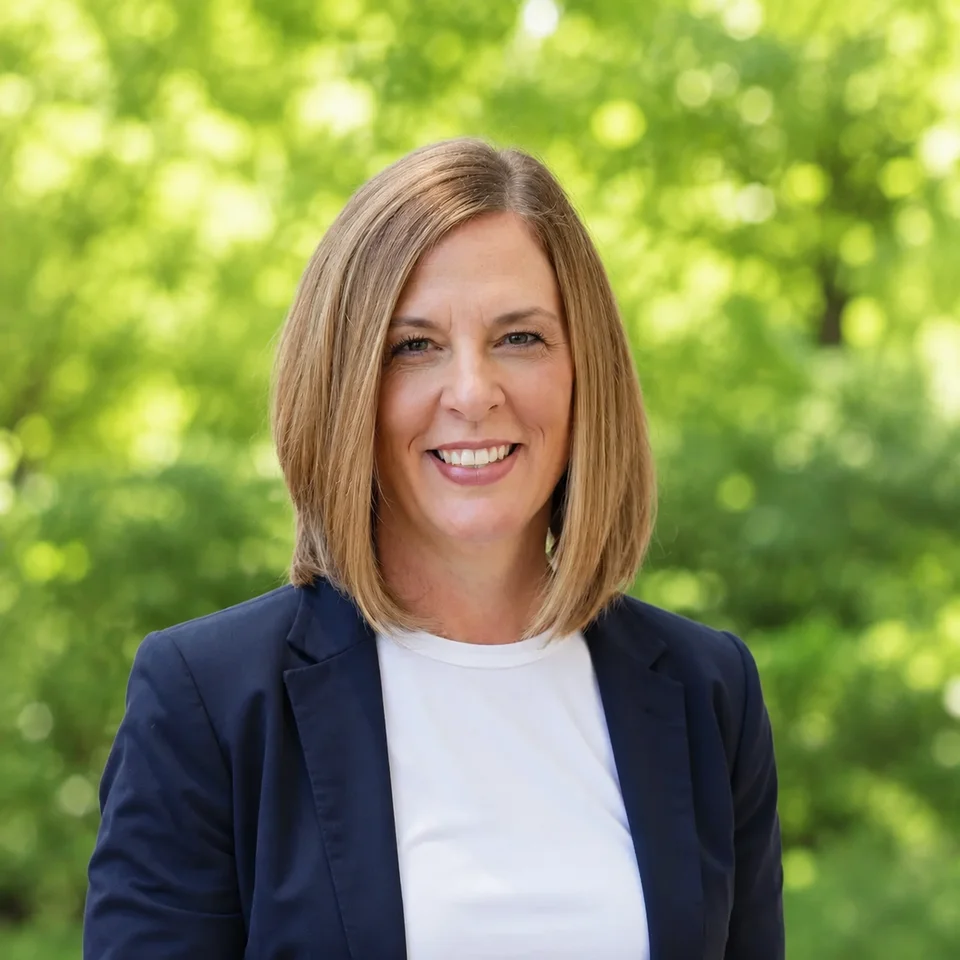
About Michelle Haigh
President, Senior Licensed Paralegal
Michelle has led Precision Paralegal Services since 1996. Her experience spans Small Claims Court, professional leadership and mentoring paralegals. She served 12 years as a Law Society of Ontario Paralegal Bencher and received the William J. Simpson Distinguished Paralegal Award in 2020.
View Michelle’s profile →Get Expert Advice
Have a matter that requires this level of precision?
Our team applies the same strategic rigour to every file. Book a consultation to discuss your situation.