The Untapped Value of L2 and L10 Applications for Insurers
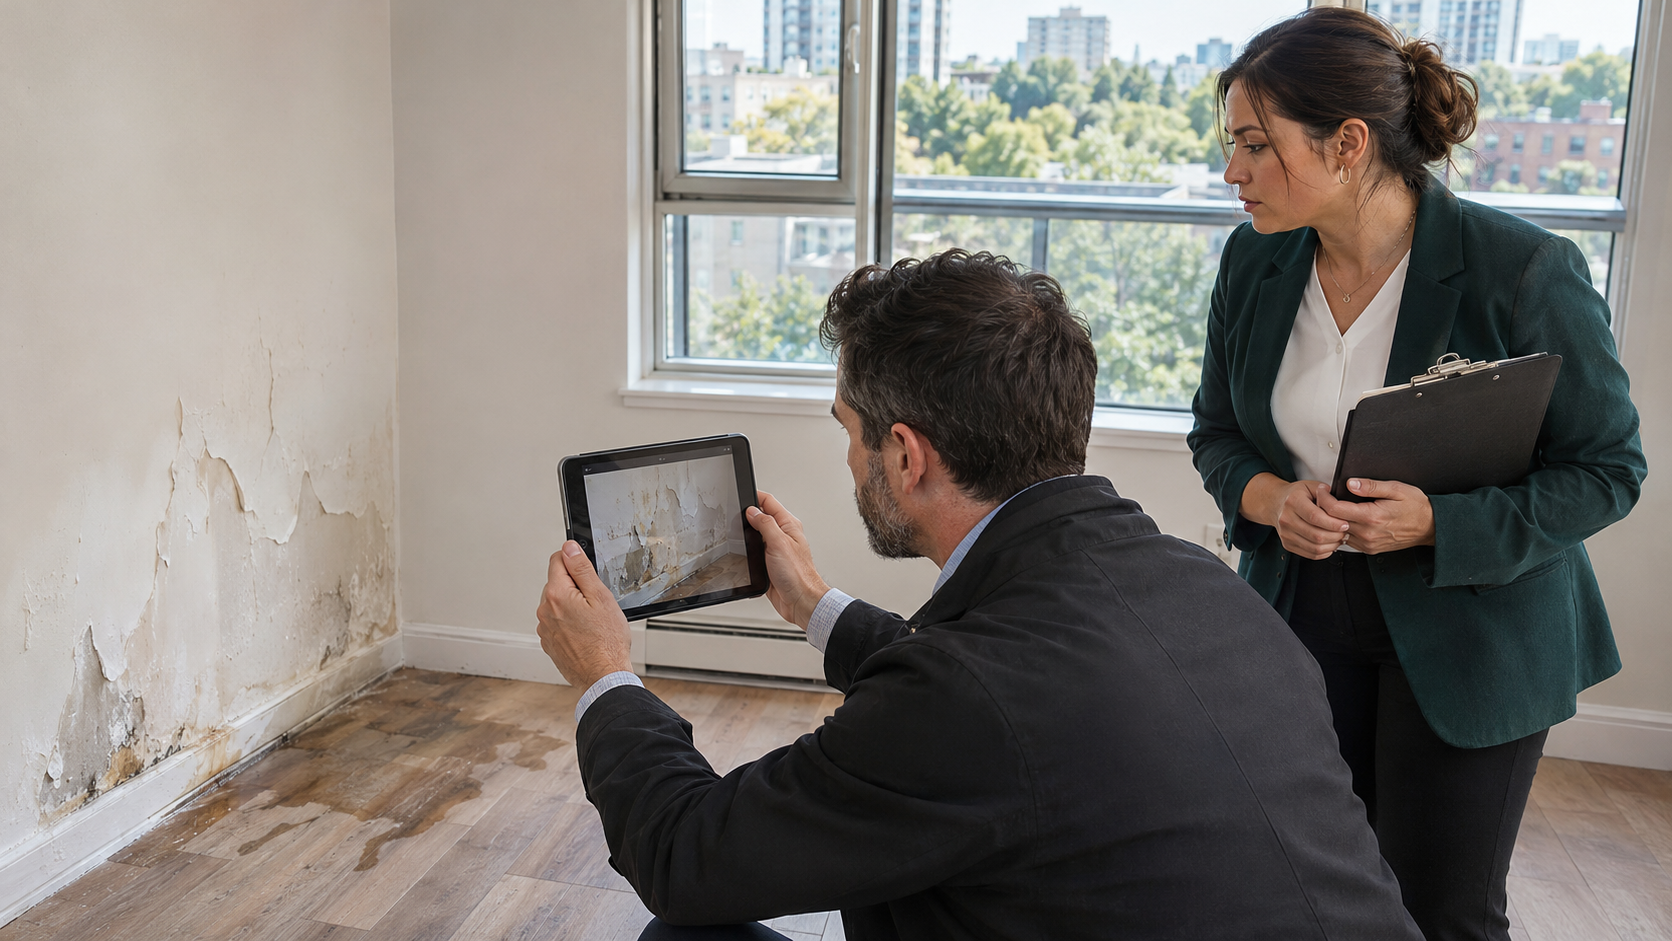
A landlord’s insurer pays a property claim, and the recovery file points toward a tenant. The repair invoices are assembled, the photographs are available and the next step may seem obvious: pursue the money through Small Claims Court.
Before filing, stop at the jurisdiction question. In Ontario, certain residential tenancy disputes fall within the Landlord and Tenant Board’s authority. Choosing the wrong forum can consume time and budget before the merits are ever considered.
For insurers reviewing tenant-caused losses, L2 and L10 applications deserve a place in the initial assessment. They are not interchangeable forms, and an insurance payment does not automatically establish liability or a right to recover through the LTB.
Check the tenancy and the recovery right first
Establish the rental arrangement, the parties, the loss and the relief sought. Does the Residential Tenancies Act apply? What right did the insured landlord have, and how does the insurer propose to pursue it through subrogation?
Review the policy, payment and recovery documentation, the proper applicant and any barriers to a claim against the particular tenant. Do not assume the insurer can simply substitute its own name on a landlord’s application. Coverage and subrogation issues need assessment alongside the forum.
The Residential Tenancies Act and the LTB’s current instructions provide the starting framework. This article concerns Ontario; Alberta and BC use their own tenancy laws and processes.
L2: assess the available remedies during the tenancy
The L2 application instructions describe an application to end a tenancy and evict a tenant or collect money. For eligible monetary claims, a landlord can seek payment without also seeking eviction. Tenant possession at filing matters, and the instructions distinguish the route for a former tenant.
Damage claims require evidence of undue damage caused wilfully or negligently by the tenant, a guest or another occupant. Normal wear and tear does not qualify. A damaged surface or an insurer’s payment alone does not establish those requirements.
If termination is also being considered, the applicable grounds, notices and filing requirements require their own review. A recovery file should not treat eviction as an automatic consequence of property damage.
L10: identify the move-out date immediately
The L10 application concerns money a former tenant owes. Eligible claims can include repair or replacement costs for property damaged wilfully or negligently by the former tenant, a guest or another occupant.
The instructions state that the tenant must have moved out on or after September 1, 2021, and that the application cannot be filed more than one year after move-out. Record that date at intake. Do not wait for the insurer’s recovery review to finish before checking the deadline, and do not assume payment of the insurance claim restarts it.
The former tenant must also be given the application and hearing materials through an authorized method. Confirm service and evidence-disclosure requirements early, rather than treating filing as the end of preparation.
Build evidence around responsibility and reasonable cost
The file should explain what happened, who is legally responsible and how the amount claimed was calculated. A practical evidence package may include:
- The tenancy agreement and documents identifying the landlord and relevant occupants.
- Move-in, pre-loss and move-out inspection records, with dated photographs.
- Incident reports, witness accounts and communications about the damage.
- Repair estimates, itemized invoices and proof of work or payment where available.
- Evidence addressing causation, the property’s prior condition and the reason for repair or replacement.
- Policy, payment and recovery records needed to establish the subrogated claim.
Separate the claimed loss from routine turnover work, pre-existing damage and improvements. Where technical issues are disputed, consider what qualified evidence is needed to explain them. An organized file makes it easier to identify both its strengths and the gaps that could defeat recovery.
Check value, jurisdiction and collectability together
The LTB’s current L2 instructions state a $50,000 monetary maximum for the claim and warn of the consequences of obtaining an order at the limit where more is owed. Review the full claim before abandoning any amount. The size of an insurance payment alone does not determine the proper forum or recoverable sum.
The original opportunity is practical: make LTB review part of property-claim intake so suitable recoveries are assessed before deadlines pass or files are written off. Neither an application nor an order guarantees collection. Consider the evidence, likely cost, settlement options and the respondent’s ability to pay.
Our insurance subrogation practice helps insurers assess eligible recovery matters. For wider recovery economics, see our article on the $50,000 Small Claims limit and subrogation. Book a consultation to review a tenant-damage file and the appropriate next step.
About Michelle Haigh
President, Senior Licensed Paralegal
Michelle has led Precision Paralegal Services since 1996. Her experience spans Small Claims Court, professional leadership and mentoring paralegals. She served 12 years as a Law Society of Ontario Paralegal Bencher and received the William J. Simpson Distinguished Paralegal Award in 2020.
View Michelle’s profile →Get Expert Advice
Have a matter that requires this level of precision?
Our team applies the same strategic rigour to every file. Book a consultation to discuss your situation.