“It’s Broken, So I’m Not Paying” — The Borrower’s Favourite Line
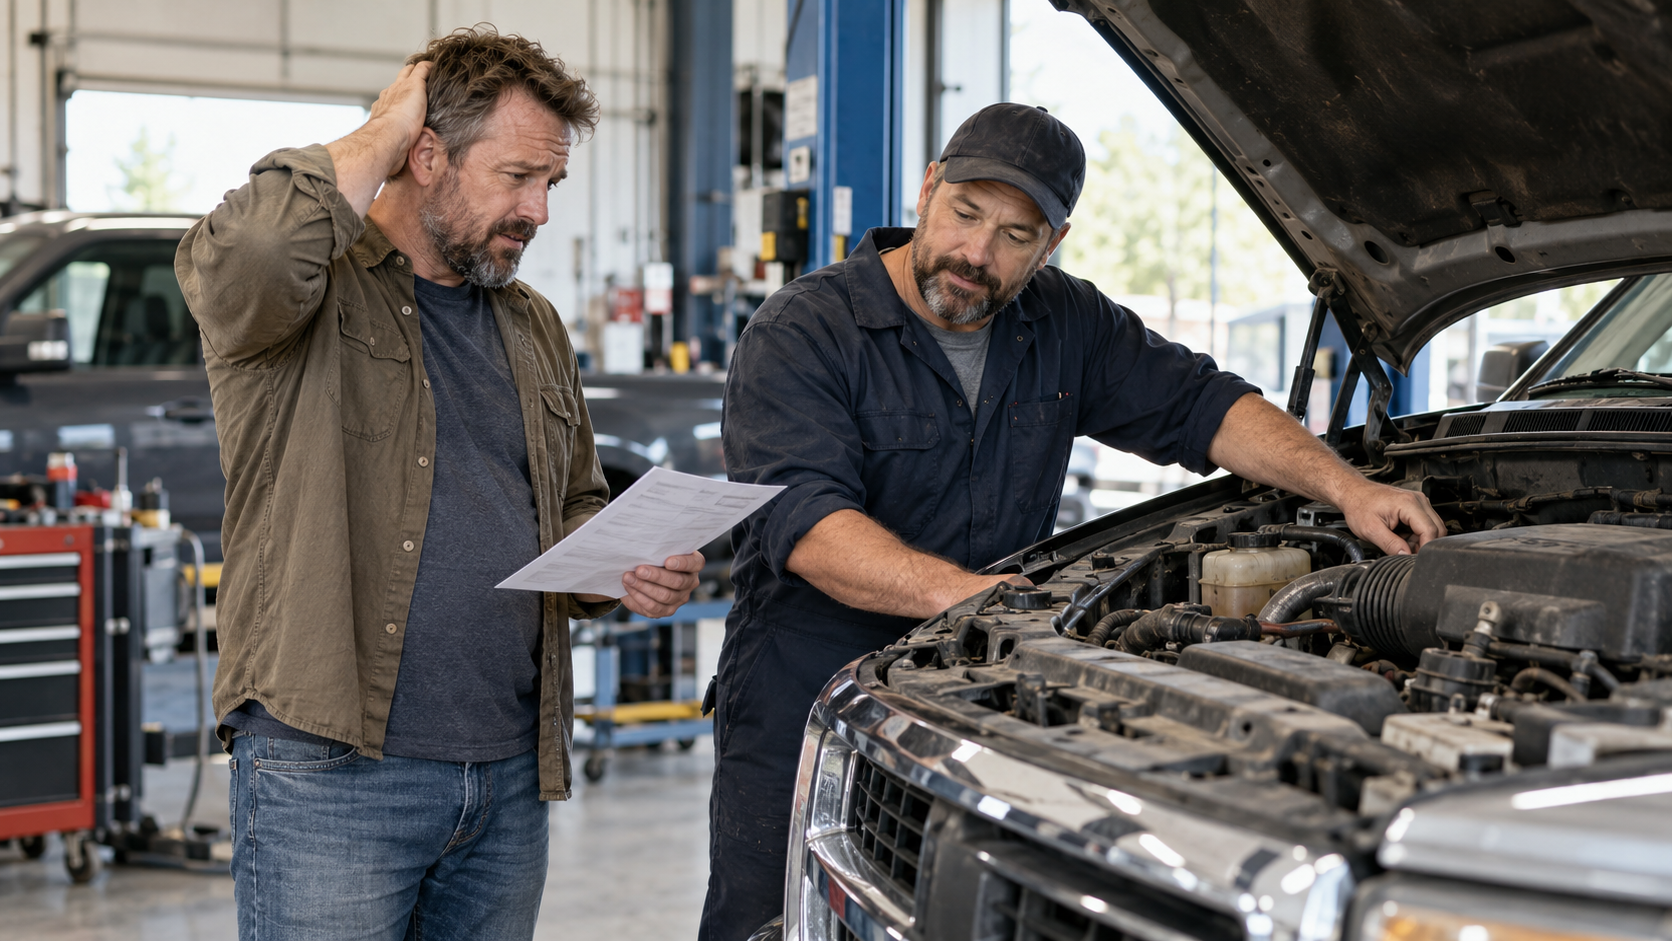
“The car’s not working.” “The equipment broke down.” And then comes the part the lender was expecting: “So I’m not making any more payments.”
If you work in auto or equipment finance, the conversation will sound familiar. Nobody enjoys paying for a truck, excavator or sedan that is sitting idle. A breakdown can create real pressure, especially when the asset is needed to earn income.
But financing is not automatically a “pay only while it works” arrangement. A mechanical problem does not, by itself, cancel the financing agreement or establish that nothing more is owed. For the lender, the next step is to assess the complaint and the payment obligation together, using the contract, the records and the applicable provincial law.
Separate the repair problem from the legal questions
Start by establishing what actually happened. What failed, when did it fail, and what supports the explanation? Who sold the asset, who financed it, and who made any promises about its condition or repairs?
A borrower’s rights against a seller or repairer and their obligations to a lender may raise different questions. They should not simply be treated as interchangeable. Equally, do not assume that a signed financing agreement defeats every complaint. Warranties, representations, consumer protections, the lender’s role and any assignment of the agreement may need review.
Whether the asset was acquired for personal or business use can also matter. The answer for a consumer vehicle transaction may differ from the answer for commercial equipment. Our article on Consumer Protection Act claims in Small Claims Court discusses that assessment in Ontario; Alberta and BC require their own legal review.
Watch what happens after the complaint
We see files where payments stop but the borrower continues using the vehicle or equipment. We also see the disappearing act: payments cease, explanations become harder to verify, and the lender is left trying to establish both the balance and the asset’s whereabouts.
Those patterns warrant investigation. They do not replace proof of the debt or justify dismissing a genuine defect. Ask for the relevant repair diagnosis, estimate, invoices and communications, then compare the timeline with the account history.
A useful file includes:
- The signed finance agreement, schedules and relevant sale or assignment documents.
- A payment history and a clear calculation of the amount claimed.
- The borrower’s complaint and the lender’s responses.
- Repair reports, warranty correspondence and evidence of the asset’s condition and use.
- Relevant notices, security documents and any steps already taken to recover the asset.
Preserve records that may support the borrower’s position as well as the lender’s. The goal is a reliable assessment before further expense is incurred.
Choose the recovery route for the province
Where the evidence supports a debt claim, Small Claims proceedings may be an option. The relevant monetary ceilings differ:
| Province | Court and monetary limit for eligible claims |
|---|---|
| Ontario | Small Claims Court: up to $50,000 |
| Alberta | Alberta Court of Justice, Civil Division — Alberta’s small claims court: up to $100,000 |
| British Columbia | Provincial Court Small Claims: up to $35,000 |
These ceilings are not the whole jurisdictional test. The claim type, remedy, parties and filing location matter; BC’s Civil Resolution Tribunal handles most small claims up to $5,000. Our comparison of provincial court options explains why the forum deserves its own assessment.
For secured lending, review the consequences of any repossession or proposed enforcement before choosing the next step. Do not assume that taking the asset and suing for a remaining balance are both available in every province or under every agreement. Alberta’s creditor guidance illustrates why the type of secured contract matters.
Keep the decision commercial
A supported repair issue may warrant further investigation or a negotiated resolution. An unsupported refusal to pay may call for a properly documented claim. In either case, compare the likely recovery with legal costs, staff time and collectability. A judgment is a step toward recovery, not a promise of payment.
Our collections versus legal action guide offers a starting point for that decision.
“It’s broken” should open a focused review, rather than close the file. Precision Paralegal Services assists corporate lenders with eligible debt recovery matters in Ontario, Alberta and British Columbia. Book a consultation to discuss the complaint, the account records and the next practical step.
Explore our corporate debt recovery services for businesses and lenders in Ontario, Alberta and British Columbia.
About Michelle Haigh
President, Senior Licensed Paralegal
Michelle has led Precision Paralegal Services since 1996. Her experience spans Small Claims Court, professional leadership and mentoring paralegals. She served 12 years as a Law Society of Ontario Paralegal Bencher and received the William J. Simpson Distinguished Paralegal Award in 2020.
View Michelle’s profile →Get Expert Advice
Have a matter that requires this level of precision?
Our team applies the same strategic rigour to every file. Book a consultation to discuss your situation.